What happens when the founder of a billion-dollar company is no longer answerable to ordinary shareholders in the same way as everyone else? And why can one founder retain extraordinary control while another, despite building a global technology empire, can be removed from the top?
In the world of corporate governance, ownership does not always translate into control. A founder can establish a company, build it into a global brand, employ thousands of people and still find that the ultimate authority rests with a board of directors.
But some founders have found a way to protect themselves from this possibility through a corporate governance arrangement known as super-voting shares.
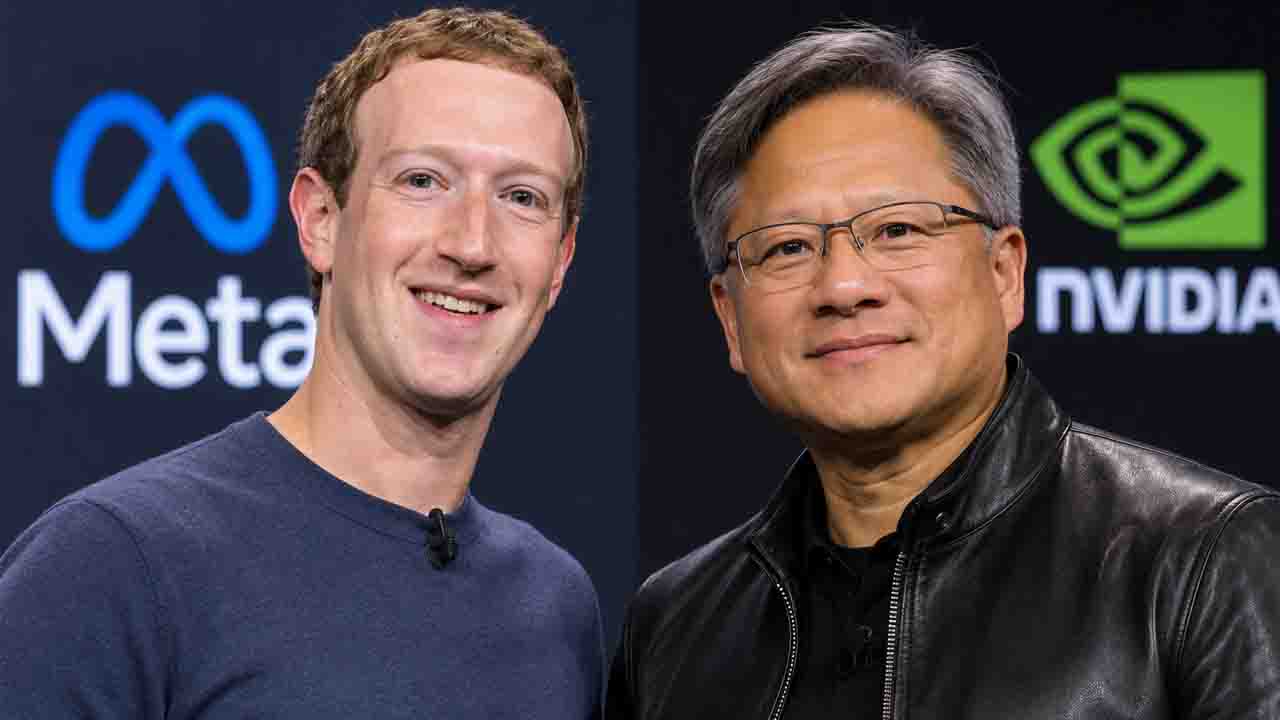
The experiences of Meta founder Mark Zuckerberg and NVIDIA co-founder Jensen Huang offer an interesting illustration of how these arrangements can shape the future of major corporations.
What exactly are super-voting shares?
Super-voting shares are a special class of company shares that carry more voting rights than ordinary shares.
In a conventional company, one share generally carries one vote. This means that a shareholder with 10% of the company’s voting shares has approximately 10% of the voting power.
However, companies with dual-class share structures operate differently.
They can issue different classes of shares with different voting rights. For example:
- Class A shares: One vote per share.
- Class B shares: Ten votes per share.
- Class C shares: No voting rights.
This means a founder can own a relatively small percentage of the company’s economic value but retain majority voting control.
The distinction is important. Economic ownership determines the financial interest someone has in a business, while voting rights determine their influence over corporate decisions.
Mark Zuckerberg: The founder who controls the board
<escape> </escape>
Meta, the parent company of Facebook, Instagram and WhatsApp, is one of the most prominent examples of a company operating a dual-class share structure.
Mark Zuckerberg owns approximately 13.4% of Meta’s economic equity, but his Class B shares carry ten votes each, compared with one vote for ordinary Class A shares.
As a result, he controls approximately 60% of the company’s voting power.
What does this mean in practical terms?
It means Zuckerberg has sufficient voting power to determine the outcome of most shareholder decisions, including the election of directors to Meta’s board.
The board of directors is ordinarily responsible for overseeing the company’s management, appointing the CEO and, where necessary, removing the CEO.
However, when one individual controls the majority of shareholder voting rights, that individual has enormous influence over who occupies the boardroom.
In Zuckerberg’s case, shareholders who disagree with his leadership cannot simply combine their ordinary shares and vote him out.
They would need to overcome his voting majority or change the company’s governance arrangements through the appropriate legal and corporate processes.
This is why Zuckerberg is often described as being exceptionally difficult to remove from Meta’s leadership.
It is not that he is legally untouchable. Rather, the voting structure makes it extremely difficult for other shareholders to challenge his control.
In October 2026, Meta also disclosed plans to introduce non-voting Class C shares, allowing it to raise capital and issue shares for strategic purposes while preserving Zuckerberg’s voting power.
The arrangement demonstrates just how important founder control remains to Meta’s corporate structure.
Jensen Huang: Building an empire does not guarantee control
<escape> </escape>
The experience of Jensen Huang, NVIDIA’s co-founder, offers a contrasting example.
Huang helped establish NVIDIA in 1993 and spent more than three decades building it into a global leader in graphics processing and artificial intelligence computing.
Despite his enormous contribution, Huang did not have the same voting protection as Zuckerberg.
NVIDIA operates a conventional one-share, one-vote structure. Huang’s ownership of approximately 3.6% of the company meant that his voting power was tied to his actual shareholding.
Unlike Zuckerberg, he did not control the majority of shareholder votes or possess a special class of super-voting shares.
This distinction became particularly important in November 2026.
Following reports concerning Huang’s personal relationships and questions that prompted an independent investigation, NVIDIA announced a leadership transition.
On November 12, the company confirmed that Huang had resigned as president, CEO and a member of the board, effective immediately.
Chief Financial Officer Colette Kress was appointed interim CEO, while Harvey C. Jones became the company’s first board chairman.
The circumstances surrounding Huang’s departure attracted considerable attention because they highlighted an important corporate governance reality: even the founder of a hugely successful company can be subject to the authority of its board.
Huang’s position as co-founder did not automatically guarantee him permanent control of NVIDIA.
His influence came from his leadership, experience, shareholding and contribution to the business, rather than an enhanced voting structure that could protect him from a shareholder-led challenge.
The difference between Zuckerberg and Huang was not simply their business achievements. It was the corporate governance structures under which their companies operated.
Why would founders want super-voting rights?
For entrepreneurs, particularly those establishing technology companies, super-voting shares can be an attractive proposition.
There are several reasons.
1. Protecting the founder’s vision
Building a successful company often requires long-term decisions that may not produce immediate financial returns.
A founder may want to invest heavily in research, technology, infrastructure or expansion.
Super-voting rights can help protect these decisions from shareholders who may prioritise short-term financial performance.
2. Preventing unwanted takeovers
A founder who controls the majority of voting rights can make it more difficult for external investors to take control of the business without their agreement.
3. Maintaining strategic direction
Founders often believe they understand the company’s original vision better than anyone else.
Super-voting shares allow them to retain significant influence even as the company attracts outside investment.
4. Raising capital without surrendering control
A company can sell ordinary shares to investors while the founder retains enhanced voting rights through a separate class of shares.
This can make it possible to raise substantial capital without giving investors equivalent control over corporate decisions.
But are super-voting rights always a good thing?
Not necessarily.
While they protect founders, they can also create governance problems.
Investors may put money into a company without having meaningful influence over its leadership.
A founder with majority voting control may be difficult to challenge, even when shareholders disagree with important decisions.
There is also the question of accountability.
If a CEO is not sufficiently accountable to the board or shareholders, who ensures that decisions are being made in the best interests of the company?
This is one of the major criticisms of dual-class share structures.
Supporters argue that founders need freedom to pursue ambitious long-term strategies. Critics argue that no individual should have excessive control over a publicly traded company without appropriate accountability.
Both arguments raise important questions about the balance between entrepreneurial freedom and corporate governance.
What does this mean for African entrepreneurs?
For African entrepreneurs building businesses they hope to expand across borders, the discussion around super-voting rights is worth understanding.
As businesses grow, founders may need to attract investors, bring in strategic partners and raise capital.
But investment often comes with expectations around ownership, decision-making and control.
A founder who gives away too much control too early may eventually find themselves in a position where investors or the board can determine the future of the business without their agreement.
On the other hand, retaining excessive control can discourage investors who want meaningful participation in corporate governance.
The solution is not necessarily to copy Meta’s structure. It is to understand the available corporate governance options and make deliberate decisions before accepting investment.
Founders should seek appropriate legal and financial advice when structuring different share classes, shareholder agreements, voting arrangements and board responsibilities.
The bigger lesson: Ownership is not the same as control
The stories of Mark Zuckerberg and Jensen Huang demonstrate an important lesson in entrepreneurship.
You can build a company without necessarily controlling it forever.
You can own a significant percentage of a business and still be answerable to its board.
And you can own a smaller percentage of a company while retaining the power to influence almost every major corporate decision.
Zuckerberg’s position at Meta and Huang’s departure from NVIDIA illustrate two very different outcomes of corporate governance.
For entrepreneurs, the lesson is simple: when building a business, it is important to think not only about how much of the company you own, but also about who has the authority to make decisions, appoint directors and determine the company’s future.
Because in business, the person who owns the most shares is not always the person who has the most power.
Editorial note: This article discusses corporate governance and publicly reported developments, not legal advice. Shareholder rights and director-removal procedures depend on the company’s constitution, jurisdiction and applicable law.